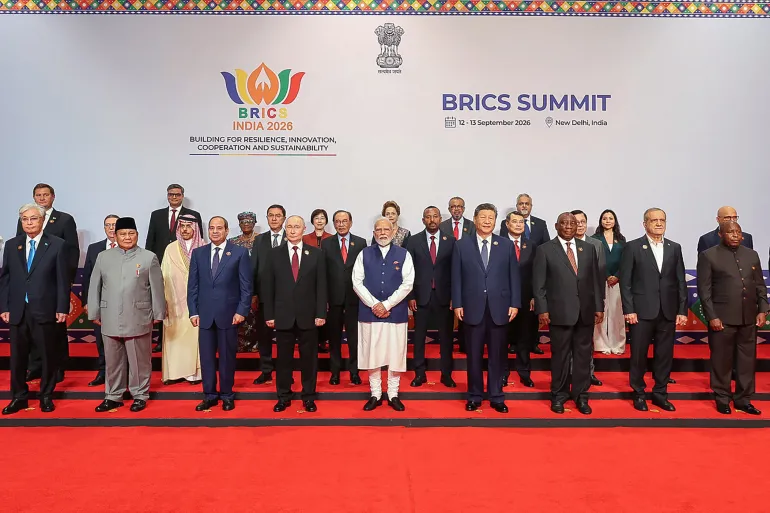
The central theme of the BRICS bloc of nations is to push back against the global economic dominance of Western countries. That core value was very much at the centre of this year’s 18th BRICS Summit, which took place last week in India.
At the September 12 and 13 summit in New Delhi, leaders committed to expanding local currency trading systems and cross-border payment systems by investing in BRICS Pay, an initiative of the BRICS Business Council.
They also encouraged the BRICS Payments Task Force (BPTF), a collaborative central bank expert platform focused on cross-border payment mechanisms, to “facilitate practical solutions for cross-border payments among BRICS countries, which are fast, low-cost, more accessible, efficient, transparent and safe”.
Manoj Kewalramani, chairperson of Bengaluru-based think tank Takshashila Institution’s Geostrategy Programme, told Al Jazeera that the declaration indicates “that the quest is not for a single system, but perhaps a suite of options that can be agreed between member states to de-risk their trade and financial dealings”.
While the New Delhi declaration did not indicate that BRICS nations aim to replace the dollar or build their own common currency, it highlights how BRICS is increasingly trying to find alternate payment systems amid geopolitical tensions and Western trade sanctions on members of the bloc, Russia and China.
If systems like BRICS Pay become fully operational, they could work as alternatives to Western payment systems like SWIFT, however.
What is BRICS Pay and how will it work?
What is BRICS Pay?
Proposed by the BRICS Business Council in 2018, BRICS Pay is a decentralised digital payment ecosystem developed to simplify payments between BRICS countries.
BRICS stands for Brazil, Russia, India, China and South Africa, the initial members of the informal trading group. It was founded in 2006, with South Africa joining in 2010. Since then, more countries have joined – Egypt, Ethiopia, Iran, Saudi Arabia, the United Arab Emirates and Indonesia.
In all, that’s 11 member countries, accounting for roughly 49 percent of the world’s population and about 40 percent of the world’s gross domestic product (GDP).
According to the BRICS Pay website, it is a “strategic infrastructure” which can also be used by “friendly states” of BRICS countries. It is also meant to offer a “compatible option” for Western payment systems like SWIFT, Visa and Mastercard, but does not intend to replace them.
The payment system was officially endorsed by the BRICS Business Council in 2024 and in August this year, before the BRICS summit in New Delhi, the group’s finance ministers and central bank officials met in Jaipur, India, to discuss advancing the project.
It is currently in pilot and phased rollout stages and is not yet globally operational for all members.
How will BRICS Pay work?
BRICS Pay will connect national payment systems of member countries to each other so international payments can be made more easily.
This will mean that trading transactions between entities or individuals in two different countries can be processed in local currencies, removing the involvement of other currencies such as the dollar.
Payments in local currencies will be settled using QR codes, digital wallets or mobile applications.
Andrey Mikhaylishin, the CEO of BRICS Pay, told India’s Asian News International (ANI) on September 12 that many countries want to use their own payment infrastructure in this way.
“For example, Russia has Mir and a Fast Payment System. India has RuPay and UPI. Furthermore, the European Union is building its own payment infrastructure, called the European Payments Initiative. The UK also wants to create and build its own infrastructure,” he noted, adding that these systems, however, do not automatically work with each other.
“BRICS Pay is a payment ecosystem that can connect national payment infrastructures and give people the ability to use them when they are travelling in countries, not only within BRICS but around the world. It’s helpful for tourists who come to the country and gives them the service of using their own domestic means of payment,” he explained.